

OneBlinc - Financial tools
by OneBlinc
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
If you are looking for a way to handle a short cash gap before your next payday, OneBlinc is designed around a simple idea: connect your account and request access to part of your earned wages. I found the app easy to understand at a glance, but it is important to approach it as a financial tool for timing problems, not as a replacement for regular income or a long-term budgeting system.
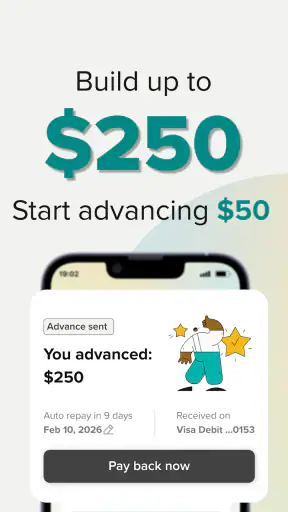
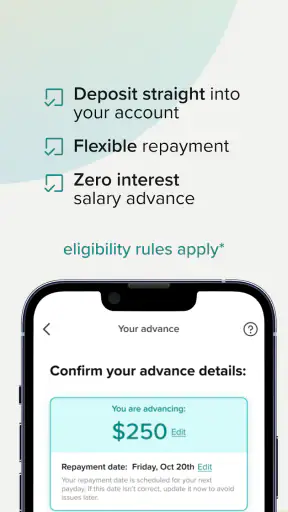
Developed by OneBlinc, this free finance app is available to users in the Everyone age group. Its central promise is access to wages of up to 250 dollars through a linked account. That makes it most relevant when an ordinary expense arrives a little earlier than expected, such as groceries, transport, or a bill that cannot wait until payday.
The app has reached over 100 thousand installs and holds a 4.6 average from around 4.8 thousand ratings, which suggests that many users find the basic experience useful. I would still read the details carefully before requesting money, because convenience in financial apps can make it tempting to act faster than you have planned.
What to expect before you connect an account
OneBlinc is not presented as a general-purpose banking app. I would think of it as a focused bridge between work income and the moment you actually need to spend it. The meaningful result is not simply opening the app; it is completing the setup well enough to understand whether you can access funds and how that action fits your next paycheck.
The first screen or two should be approached with a practical question in mind: “What problem am I solving today?” If the answer is a small, temporary shortfall, the app may be worth exploring. If you need help reducing debt, building savings, tracking every category of spending, or planning several months ahead, a traditional budgeting app or your bank’s own tools may be a better starting point.
Because the app works with a linked account, the quality of your first experience depends on having the correct account information available. I would not begin while rushing between errands. Set aside a few minutes, make sure you can identify the account you intend to use, and keep your employment and payment details consistent with what you normally use for financial services.
One useful habit is to decide your repayment plan before you make a request. Even when the amount feels modest, it still affects the money available to you later. I prefer to write down the upcoming payday and the expenses that must be covered from it. That small step turns the app from an impulse button into a deliberate short-term choice.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
How the first setup feels
After installing the current version, 7.12.0, I would move through the account connection process slowly rather than tapping through every screen automatically. The app’s purpose is narrow, so each piece of information has a direct relationship to eligibility, account access, or receiving funds. If a screen asks you to review details, read it instead of assuming it is routine.
The minimum operating system is Android 7.0, so the app can work on many older Android phones. That is helpful if you do not own a recent device, although an older phone may make banking screens less comfortable to read. I would also keep the operating system and the app updated where possible, especially when dealing with account connections.
During setup, use the account that you actually expect to receive or manage money through. Choosing an account simply because it is the first one shown can create confusion later. A good check is to compare the account name and ending details with your own banking app before continuing.
Do not treat a successful connection as proof that you should immediately request the maximum amount. First confirm that the account shown is the one you intended to use and that the available action matches your need. The difference between requesting a small bridge and taking the full available amount can matter when your next paycheck arrives.
What to do when setup does not go smoothly
Financial app setup can fail for ordinary reasons: an account may be entered incorrectly, a connection may need another attempt, or the information you provide may not match the records used for verification. My first response would be to stop repeating the same action. Recheck the account, confirm that the phone has a stable connection, and make sure there are no typing errors.
If the problem continues, I would avoid creating several accounts or submitting repeated requests in frustration. That makes it harder to understand what happened. Instead, note the exact screen where the process stopped and use the app’s available support path. Keeping a screenshot for your own reference can also make an explanation clearer, provided it does not expose sensitive account information.
A particularly sensible precaution is to hide or remove personal financial details before sharing a screenshot. Never send a full account number, password, security code, or other private credential in a support message. The app may help with wage access, but ordinary digital-safety habits still apply.
Making the first successful request
The first meaningful success is not merely seeing a balance or finishing registration. It is understanding the amount you can request, choosing an amount that solves the immediate problem, and knowing what that choice means for the money you will have later.
Imagine that your car needs fuel to get you to work, but your paycheck is still several days away. I would open OneBlinc, confirm the linked account, review the amount available, and request only what covers that specific need. If the app presents a confirmation step, I would read the timing and destination details before approving anything.
This is where the app’s focused design is useful. You do not need to build a large financial plan before dealing with a small timing gap. At the same time, the narrow focus is also its limitation: the app cannot make an unaffordable expense affordable. It only changes when part of your wages becomes available.
Before confirming, compare the requested amount with your next payday obligations. Rent, utilities, food, transport, and existing commitments should come first. If taking money early would leave you short immediately after payday, I would skip the request and look for another solution, such as asking the bill provider for a different due date or using a savings buffer.
Once a request is submitted, keep an eye on the linked account and the app’s status information rather than assuming that everything is instant. The store summary focuses on direct access to a linked account, but real financial actions still depend on the details of your account and the request. A confirmation screen is not the same thing as money already available for spending.
Choosing an amount without creating a new problem
The maximum available amount can be useful in a genuine emergency, but it should not become the default selection. I recommend starting with the exact cost of the need, plus only a small margin if the expense is uncertain. For example, if you need to cover a specific grocery trip, estimate that trip instead of automatically choosing the largest figure.
This approach has a practical advantage: it makes the next payday easier to manage. A smaller early request leaves more of your wages untouched, which reduces the chance that you will need another advance to cover ordinary expenses. In my view, that is the most important discipline for using this kind of service responsibly.
Another helpful workflow is to record the request in your normal budget immediately. Label it as money received early, not as extra income. That distinction prevents the amount from disappearing into general spending and gives you a clearer picture of what the next pay period will look like.
If you share finances with a partner or family member, tell them about the request before the money is spent. This is especially useful when the linked account is used for household bills. A small advance can affect a joint balance even when the original expense seems personal.
Where first-time users may become confused
One common misunderstanding is treating wage access as the same thing as earning more. It is not. The money is connected to wages you expect to receive, so taking it earlier changes the timing of your cash flow. I would explain it to a friend as moving part of the next paycheck forward, not adding a new source of income.
Another possible confusion is the difference between being able to use the app and being able to request money. Installing a finance app does not automatically mean every action will be available. Account connection, eligibility checks, and the information associated with your wages can affect what you see. If the amount shown is different from what you expected, review the displayed details instead of assuming the app is malfunctioning.
Users may also focus on the headline amount and overlook delivery or account information. Before accepting anything, check where the money is going and whether the timing suits the expense. If the need is happening right now, a request that arrives later may not solve it; if the expense can wait, rushing may be unnecessary.
I would also avoid comparing OneBlinc only with a credit card limit. A credit card can provide a reusable line for purchases, but it may encourage spending beyond the next paycheck and can carry interest depending on how it is managed. OneBlinc’s appeal is more specific: it is aimed at accessing wages earlier through a linked account. Neither option is automatically better; the right choice depends on whether you need a controlled bridge or flexible borrowing for a larger purchase.
How it compares with familiar alternatives
Compared with a standard bank overdraft, the app may feel more intentional because the action is centered on accessing wages rather than simply allowing an account balance to fall below zero. An overdraft can be convenient for an unexpected payment, but it can also make it harder to notice how much you have spent. OneBlinc is easier to understand when you use it for a defined amount and a defined reason.
Compared with a personal loan, the process is suited to a much smaller and shorter cash-flow problem. A loan may be more appropriate for a planned expense that requires a larger sum and a formal repayment schedule. Using a wage-access tool for that kind of need would not be my recommendation.
Compared with a budgeting app, OneBlinc addresses the immediate availability of money rather than showing a complete picture of spending. I would happily use a budgeting tool alongside it, not instead of it. The budget tells you whether the request is sensible; OneBlinc can help with the timing when the answer is yes.
Compared with borrowing from a friend, the app offers a more structured digital route, but it does not remove the need for judgment. A trusted person might offer flexibility that an automated financial service cannot. On the other hand, not everyone has that option, and a clearly presented wage-access process can be useful when the gap is temporary and the account details are in order.
Who will get the most from it
I think OneBlinc is best for someone with regular wages who occasionally faces a mismatch between payday and necessary expenses. The strongest use case is a contained problem: a bill, commute, or essential purchase that can be covered by a modest early portion of income and will not destabilize the following pay period.
It may also suit users who prefer handling a financial request from a phone instead of visiting a branch or arranging an informal loan. The free installation lowers the barrier to trying the service, and the Everyone rating makes the app broadly approachable from an age-classification perspective.
I would be more cautious if your income changes sharply from one pay period to the next, if you already rely on advances frequently, or if your regular expenses consume nearly every paycheck. In those situations, early access can hide a deeper budget problem. A conversation with a financial counselor, a revised spending plan, or a safer emergency fund strategy may help more than another short-term request.
The app is also not my first choice for building credit, tracking investments, comparing insurance, or managing a complete household budget. Its value comes from a particular job, and staying within that job is what makes it easier to use responsibly.
Small habits that make the app safer to use
My first recommendation is to create a personal limit below the amount the app may show. The available amount is not necessarily the amount you should take. A self-imposed ceiling based on your next payday can prevent an urgent moment from turning into a larger cash-flow problem.
Second, use a “reason before request” rule. Write the expense in one sentence, such as “fuel for work travel” or “food until payday.” If you cannot name the expense clearly, wait. This simple pause is more useful than relying on willpower after the money has already arrived.
Third, review the linked account after the transaction and again around payday. That gives you a practical confirmation that the money went where you expected and helps you notice how the early access affected your balance. It is a small piece of record-keeping, but it prevents the request from becoming invisible in everyday spending.
Finally, protect access to the phone and the account. Use your device’s normal security controls, avoid financial activity on an unfamiliar network when possible, and do not share login details with anyone who offers to “help” you complete a request. The convenience of a mobile finance app should never outweigh basic account security.
My recommendation after using it
OneBlinc makes sense when the problem is timing rather than a lack of income. I like the directness of its purpose: connect a linked account, understand what is available, and decide whether receiving part of your wages early solves a specific need. That clarity is more useful than a crowded finance app when you only need a short bridge.
My main reservation is equally direct. The app can make access feel easy, and easy access can encourage repeated use. If you find yourself opening it every pay period just to make ordinary bills fit, I would treat that as a warning sign and step back to review your budget. The most successful use is occasional, planned, and tied to an expense you can explain.
The rating and install history show that the app has attracted a substantial audience, while the current release indicates that it continues to be maintained. Those details are reassuring for someone considering the service, but they should not replace your own review of the account and request screens.
If you decide to try it, begin with the smallest realistic need. Complete the account setup carefully, confirm the destination, read the final request details, and record the amount in your budget. If that first transaction helps you reach payday without creating a new shortage, you have learned what the app is good at. If it only postpones the same problem, a different financial solution will be the better next step.
Overall, I would recommend OneBlinc to a first-time user who needs a controlled way to handle an occasional gap and is comfortable planning around the next paycheck. I would skip it for long-term borrowing or repeated bill coverage. Used with restraint, it is a focused financial tool; used automatically, it can make an already tight budget harder to see clearly.
Pros
- Early paycheck access can help cover urgent expenses before payday.
- Personalized tools may help users monitor spending and manage cash flow.
- The app offers convenient access to financial services from a phone.
- Automated features can reduce the effort needed to track account activity.
- Useful for users seeking alternatives to traditional short-term credit.
Cons
- Eligibility requirements may exclude users with limited income or credit history.
- Fees, interest, or subscription costs can make borrowing expensive.
- Availability and features may vary depending on location and employer.
- Cash advances can encourage repeated borrowing and create repayment pressure.
- Users may need to share sensitive financial and employment information.
FAQs for OneBlinc - Financial tools
What is OneBlinc, and what financial tools does it offer?
OneBlinc is a financial services app designed to help eligible users manage short-term cash needs and everyday money matters from a mobile device. Depending on eligibility and availability, its tools may include cash advances, a spending account or debit card, budgeting features, credit-building options, and access to financial insights. The exact products, limits, fees, and terms can vary by user and location.
Who can use OneBlinc, and what information is required to sign up?
OneBlinc is generally intended for eligible adults in the United States, although requirements can change according to the product and applicable regulations. During registration, the app may request personal identification details, contact information, employment or income data, and permission to connect a bank account. Approval is not guaranteed, and users should review eligibility conditions and privacy disclosures before submitting sensitive information.
Does OneBlinc charge fees, interest, or membership costs?
The cost of using OneBlinc depends on the specific feature selected and the terms shown in your account. Some services may involve a subscription, expedited-transfer charge, optional tip, card-related fee, or other cost, while certain features may be available without a traditional interest charge. Before confirming a transaction, carefully check the displayed pricing, repayment schedule, and applicable disclosures rather than assuming every tool is free.
How do OneBlinc cash advances and repayments work?
If you qualify for a cash advance, OneBlinc typically shows the available amount, delivery method, expected arrival time, and repayment date before you accept it. Standard delivery may differ from an expedited option, and repayment can usually be collected automatically from a linked account on the scheduled date. Make sure sufficient funds are available, because failed payments, overdrafts, or additional charges may result.
Is OneBlinc safe to use, and what should I know about privacy?
OneBlinc may use account verification, encryption, authentication, and other security measures to protect financial information, but no online service can eliminate every risk. Read the privacy policy to understand how identity, banking, transaction, and device data are collected and shared. Download the app only from an official store, use a strong password, enable available security controls, and contact support promptly if suspicious activity appears.

OneBlinc - Financial tools
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via customer@oneblinc.com, visit https://blincadvance.oneblinc.com/, or review their https://oneblinc.com/privacy-policy.










